Tax Debt Relief Group Explains What IRS ‘Fresh Start’ Relief Covers—and What It Doesn’t
Orlando tax practice outlines offer in compromise conditions, payment plan rules and levy protections for individuals,
Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

Orlando tax practice outlines offer in compromise conditions, payment plan rules and levy protections for individuals, business owners and veterans
ORLANDO, FL, UNITED STATES, November 12, 2026 /EINPresswire.com/ — Tax Debt Relief Group, an Orlando, Florida tax practice, today released guidance explaining what the IRS “Fresh Start” label does and does not cover for individuals, business owners and veterans with unpaid federal tax debt. The IRS describes the offer in compromise as formerly known as the Fresh Start program, but the label does not mean the agency will erase or cut a tax bill for everyone who asks. The guidance responds to widespread confusion about the 2011 initiative and about what the IRS can still do through collections, liens and levies.
Online searches for the “IRS Fresh Start program” run into the tens of thousands every month, according to keyword data. Many of the ads and websites that appear promise to wipe out a tax bill. The IRS cautions taxpayers about aggressive marketing that overinflates promises of eliminating tax debt.
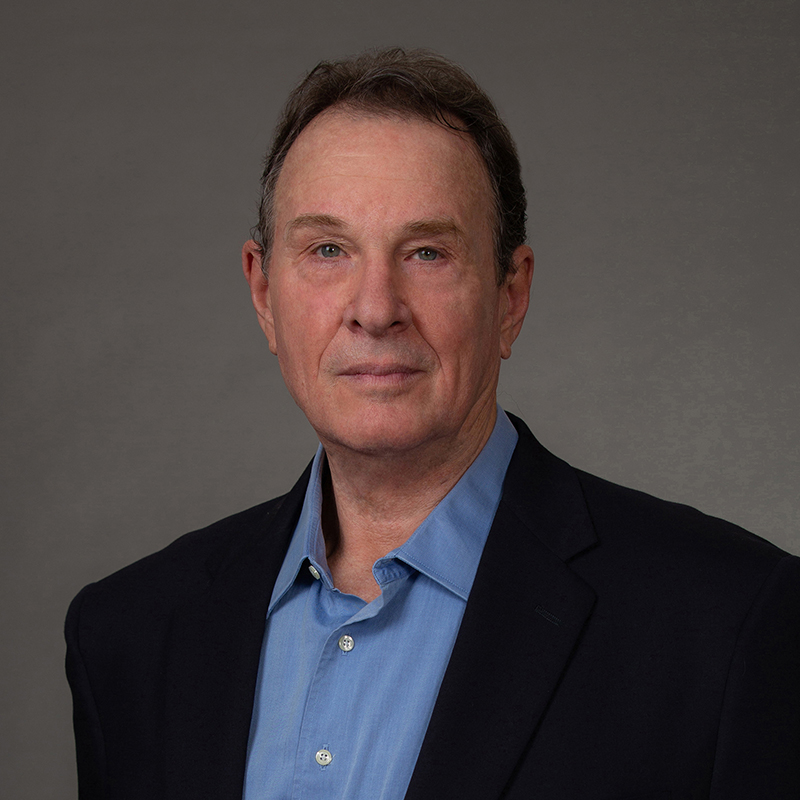
“Fresh Start was a 2011 IRS initiative, not a button anyone can push to make a balance disappear,” said Peter Kici, CEO and founder of Tax Debt Relief Group and an Enrolled Agent. “The initiative changed some lien rules and made payment options easier to reach. Whether anything helps a particular taxpayer depends on the full picture: every return filed, the income, the assets and the exact notice in the mailbox.”
What the Fresh Start label points to today
The offer in compromise lets some taxpayers settle for less than they owe, but the IRS sets firm conditions. A taxpayer must file all required returns, make required estimated tax payments and not be in an open bankruptcy. An employer must also have made required federal tax deposits for the current and last two quarters. Every application requires a $205 fee and a first payment, unless an individual meets the low-income qualifications. Generally, the IRS will not accept an offer if the debt can be paid in full through a payment plan or equity in assets. If the IRS accepts an offer based on doubt as to collectibility, the taxpayer must also file and pay on time for five years afterward.
Payment plans are the other common path. Under the Internal Revenue Manual, a simple payment plan is available without a financial statement when the unpaid balance is $50,000 or less and the plan pays the debt in full, including accruals, before the collection statute expires. Larger balances generally require the IRS to review the taxpayer’s finances.
The initiative also changed lien rules. The IRS describes withdrawal options for federal tax liens that came from the 2011 program. In IRS collections, a lien is a public claim against property. A levy is the actual seizure of money or property, such as wages or a bank account.
Protections that depend on the taxpayer
Some levy protections depend on the source of the money. Service-connected disability compensation paid by the VA is exempt from IRS levy under Internal Revenue Code Section 6334(a)(10), as the Internal Revenue Manual confirms at IRM 5.11.1.4.1. That protection covers the benefit itself. It does not erase the tax debt, and the IRS can still pursue other income and property.
Military retirement pay is treated differently. Survivor Benefit Plan annuities and the Retired Serviceman’s Family Protection Plan are listed as exempt, but general military retirement pay is not an absolute exemption. Service members in a combat zone have separate protection. Under Internal Revenue Code Section 7508, the IRS may not levy or file a federal tax lien while a taxpayer serves in a combat zone, and the collection period is extended by the service time plus 180 days (IRM 5.1.19.3.8). The Servicemembers Civil Relief Act can also defer collection for up to 180 days when service materially affects the ability to pay (IRM 5.1.19.3.9).
Business owners face their own pressure points. An employer behind on federal tax deposits cannot qualify for an offer until the deposits are current. Unpaid payroll taxes can also bring IRS collections action against the business and, in some cases, against responsible individuals under the trust fund recovery penalty in Internal Revenue Code Section 6672.
Attorneys, CPAs and Enrolled Agents may all represent taxpayers before the IRS. Consumer cautions apply to any company that guarantees a result, asks for a large upfront fee before reviewing the account, or says Fresh Start applies to everyone.
“Individuals and business owners should both get a straight answer about which protections apply, which options are realistic, and what the IRS can still do,” Kici said. “Veterans and service members have some protections of their own, and those are worth checking first. That starts with a review of the account, not a slogan.”
About Tax Debt Relief Group
Tax Debt Relief Group is an Orlando, Florida tax practice that represents individuals and businesses in IRS and state tax matters, including IRS collections, levies, liens, wage garnishments, unfiled returns and business trust fund recovery claims by the IRS. Peter Kici is an Enrolled Agent, licensed by the U.S. Department of the Treasury to represent taxpayers before the IRS, and a Marine Corps veteran.
Media Contact: Peter Kici, CEO and Founder, Tax Debt Relief Group, Orlando, FL | Pete@taxdebtreliefgroup.com | (407) 531-8705 | taxdebtreliefgroup.com
Peter Kici, Enrolled Agent
Tax Debt Relief Group
+1 407-531-8705
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery
